

SpaceX is the missing half of the Bitcoin thesis, and the two are more connected than most investors realize. This is not about Mars. It is not about moon missions. It is about control: who controls the money, who controls the network, and who controls the infrastructure that makes both possible.
The real thesis is what happens when launch costs hit $100 per kilogram, a 500x reduction from where the industry started. At that price, data centers move to orbit. Cooling becomes free. Power becomes abundant. Jurisdiction disappears. And Bitcoin, which has always had one remaining physical vulnerability, finally loses it.
Most people associate SpaceX with Mars. That is by design. The Mars narrative serves Elon Musk’s personal brand, attracts talent who want to work on civilization-scale problems, and provides regulatory cover for launch frequency. It is a story, and a useful one. But Mars generates no revenue, has no timeline, and has no customers. What SpaceX sells is access to low Earth orbit at a cost no competitor can match. That is business. Everything else flows from that.
The real thesis is the physics of (data centers) computing in space. Data centers have three fundamental problems on Earth: heat, power, and jurisdiction. Cooling alone consumes 30-40% of a typical data center’s energy budget. In space, heat directly radiates into a 3 Kelvin background, making cooling essentially free. Power density in LEO runs at 1,360 watts per square meter, compared with roughly 1,000 at Earth’s surface, with no atmospheric absorption, no weather, and no night cycle if orbits are designed correctly.
And a data center in orbit sits in no jurisdiction, governed not by local law or government access orders, but by whoever controls the encryption keys. Space solves all three simultaneously. That is not a science fiction scenario. It is an engineering and cost problem, and SpaceX is the only company that has solved the cost side.
The cost to orbit is the gating variable. Until SpaceX, putting one kilogram into LEO cost approximately $54,000 on a Delta IV. Falcon 9 brought that to $2,700. Starship, once operational at scale, aims to target below $100 per kilogram. That is a 500x reduction in 15 years. At $54,000/kg, space data centers are science fiction. At $100/kg, they are infrastructure investment decisions. The entire thesis turns on Starship’s launch economics, which is why the IPO valuation matters; the market is being asked to price not current Starlink revenue but the option value on what becomes possible when launch costs hit the floor.
Microsoft announced in 2023 that it would put Azure computing infrastructure into space via a partnership with SpaceX. This was not a press release about Mars. It was a hyperscaler acknowledging that orbital compute has a viable unit economics case. Google, Amazon Web Services, and defense contractors have made similar moves. The customers exist. The demand is real. The constraint is launch cost and launch frequency, both of which SpaceX controls.
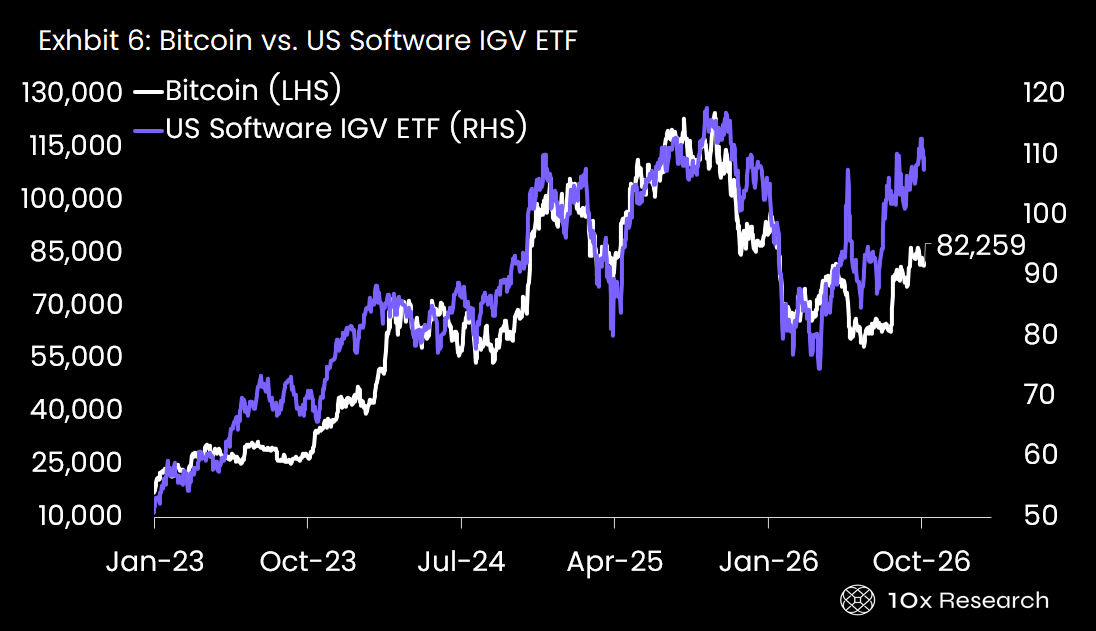
The US military, Pentagon’s Joint Warfighting Cloud Capability contract, the proliferated LEO satellite programs, and the classified payloads SpaceX already launches all point in the same direction: the DoD wants a resilient, distributed, unjammable computing and communications infrastructure that cannot be taken out by a ground strike on a fixed facility.
A ground-based data center can be bombed. The constellation of orbital compute nodes is effectively indestructible with current weapons. This is why defense primes Northrop, Raytheon, and L3Harris are all building space-based ISR and compute capabilities, and why they are all dependent on SpaceX for launch capacity.
The current objection to orbital data centers is latency. LEO is 550km up; the round-trip signal delay is ~5ms versus sub-1ms for terrestrial. For most AI inference workloads, financial settlement and data storage are irrelevant. The latency constraint only matters for high-frequency trading and real-time control systems, a small fraction of total compute demand. As laser inter-satellite links mature, Starlink is already deploying them, creating a global mesh network in which data routes through space rather than through undersea cables. For long-distance traffic, the space route is faster than fiber, because light travels faster in a vacuum than in glass. Physics favors space routing for transcontinental data transfer.
Bitcoin (LHS) vs. UFO ETF, Space ETF (RHS)
Bitcoin has a physical vulnerability. To transact, internet infrastructure is needed, and states own, route, and censor it. Undersea cables, terrestrial ISPs, and DNS servers are all points of control. A state that can cut the internet can freeze your Bitcoin. Starlink solves Bitcoin’s last physical dependency. A low-earth-orbit satellite constellation provides internet access from space, no cables, no terrestrial chokepoints, no single jurisdiction. Bitcoiners can run a BTC node and broadcast transactions from anywhere on Earth’s surface with a dish the size of a laptop. Bitcoin is not just cryptographic money, but cryptographic money running on infrastructure that no single government can shut down.
SpaceX is not just Starlink’s launcher; it is the only entity currently capable of building and maintaining a LEO constellation (network of satellites operating in Low Earth Orbit) at the required scale. Starlink has 7,000 satellites in orbit today, with regulatory approval for 42,000. No other operator is close. This creates the infrastructure monopoly, making the thesis real rather than theoretical. SpaceX holding 8,285 BTC on its balance sheet is not incidental. It signals that the company understands exactly what it is building. Starlink is the physical layer; Bitcoin is the financial layer. Together, they constitute a parallel monetary and communications infrastructure that sits outside state jurisdiction.
An orbital data center running Bitcoin nodes or financial infrastructure is the complete realization of the Sovereign Individual thesis. Not just censorship-resistant money, but censorship-resistant compute, the ability to run applications, store data, and process transactions in a jurisdiction that does not exist on any map. The combination of Starlink connectivity and orbital compute closes the loop entirely.
When SpaceX lists, the market will price it as a launch company and a satellite internet company. That is the visible business. The invisible business, the option on orbital compute, defense infrastructure, and jurisdiction-free data processing, will not be in the analyst models for the first two years.
That mispricing is the trade. Companies that understand what SpaceX is building, not a rocket company, not a Mars program, but the physical infrastructure layer for post-national computing, will be positioned before the narrative catches up to reality. The space economy is not about SpaceX going to Mars. It is about SpaceX making Earth’s surface optional for the institutions that currently have no choice but to be on it.
The tools that decentralize power and the tools that concentrate it are identical. Cryptography, satellites, and AI are simultaneously the infrastructure of liberation and the infrastructure of the most sophisticated surveillance state ever built.
Palantir was built on a single insight: governments have infinite data and no ability to use it. Palantir sells access to it. Gotham, its government platform, aggregates signals intelligence, financial flows, social graphs, and physical movement into a single operational picture. ICE uses it to track undocumented migrants. The DoD uses it to target drone strikes.
Palantir requires cooperation from the infrastructure layer. It needs telecoms to provide metadata, banks to provide transaction records, and ISPs to provide browsing data. A citizen on Starlink, paying in Bitcoin and running communications through encrypted channels, leaves almost nothing for Palantir to ingest in that infrastructure. The surveillance state’s weakness is that it depends on centralized chokepoints, and SpaceX/Bitcoin/encryption systematically eliminates them.
Bitcoin (LHS) vs. Palantir (RHS)
China has built the most complete proof of concept for the counter-thesis. The Social Credit System, the Great Firewall, digital yuan with programmable spending constraints, and Huawei’s export of surveillance infrastructure to 70+ countries represent a coherent alternative vision: AI as the enforcement layer for total state legibility. Every citizen is fully readable, fully controllable, and fully dependent on state-mediated infrastructure.
The digital yuan is the most important piece. It is not just a payment system; it is a programmable ledger that allows the state to set expiry dates on money, restrict spending by category, freeze accounts without judicial process, and monitor every transaction in real time. It is the exact opposite of Bitcoin. Same technology stack, inverted power structure.
AI is the leverage multiplier for whichever side controls the infrastructure. The race is therefore not between freedom and control in the abstract. It is between two infrastructure buildouts happening simultaneously: the decentralized stack (Bitcoin, Starlink, encryption, private compute) and the centralized stack (CBDC, Palantir, facial recognition, state-controlled AI). Whoever gets to most of the world’s population first, with their infrastructure, their defaults, their interfaces, wins the next century.
States cannot run a Chinese-style surveillance system on a population that has already migrated to Starlink connectivity, Bitcoin settlement, and encrypted compute. Palantir versus Bitcoin, digital yuan versus Starlink, state AI versus private compute, is arguably the most important investment and geopolitical question of the next decade.
Palantir is building the infrastructure that makes states more powerful, AI-enabled surveillance, targeting, and population management. SpaceX is building the infrastructure that makes states less powerful, enables unjammable communications, provides jurisdiction-free money transaction capabilities, and enables private computing. Both are using the same underlying technologies. The question is not which side wins. The question is which side you own.
Licensed to: Confidential – Licensed for the exclusive use of the recipient. Redistribution, forwarding, copying, or publication without prior written permission from 10x Research is strictly prohibited and may result in termination of the subscription.
Disclaimer: This email and any attached research are for informational and educational purposes only and do not constitute investment, financial, legal, or tax advice, or a recommendation or solicitation to buy or sell any asset. 10x Research Pte. Ltd. does not provide personalized investment advice and is not licensed or registered as a broker-dealer, investment adviser, or financial adviser in any jurisdiction. Information is obtained from sources believed to be reliable but is not guaranteed as to accuracy or completeness, and all views, estimates, and forecasts are the authors’ own as of the date of publication and are subject to change without notice. Past performance is not indicative of future results. This material is not intended for distribution in any jurisdiction where such distribution would be unlawful, and is not directed at retail investors. 10x Research and its principals may hold positions in assets discussed herein. This document is confidential and intended solely for the recipient; unauthorized redistribution is prohibited. Please consult a qualified independent professional before making any financial decision. © 10x Research.